
EXECUTIVE INTERVIEW BRIEFING | TEAM TECHNOBIZ
NOVEMBER 2026
Implementing Digital Solutions for Customers — Bank Alfalah Pakistan
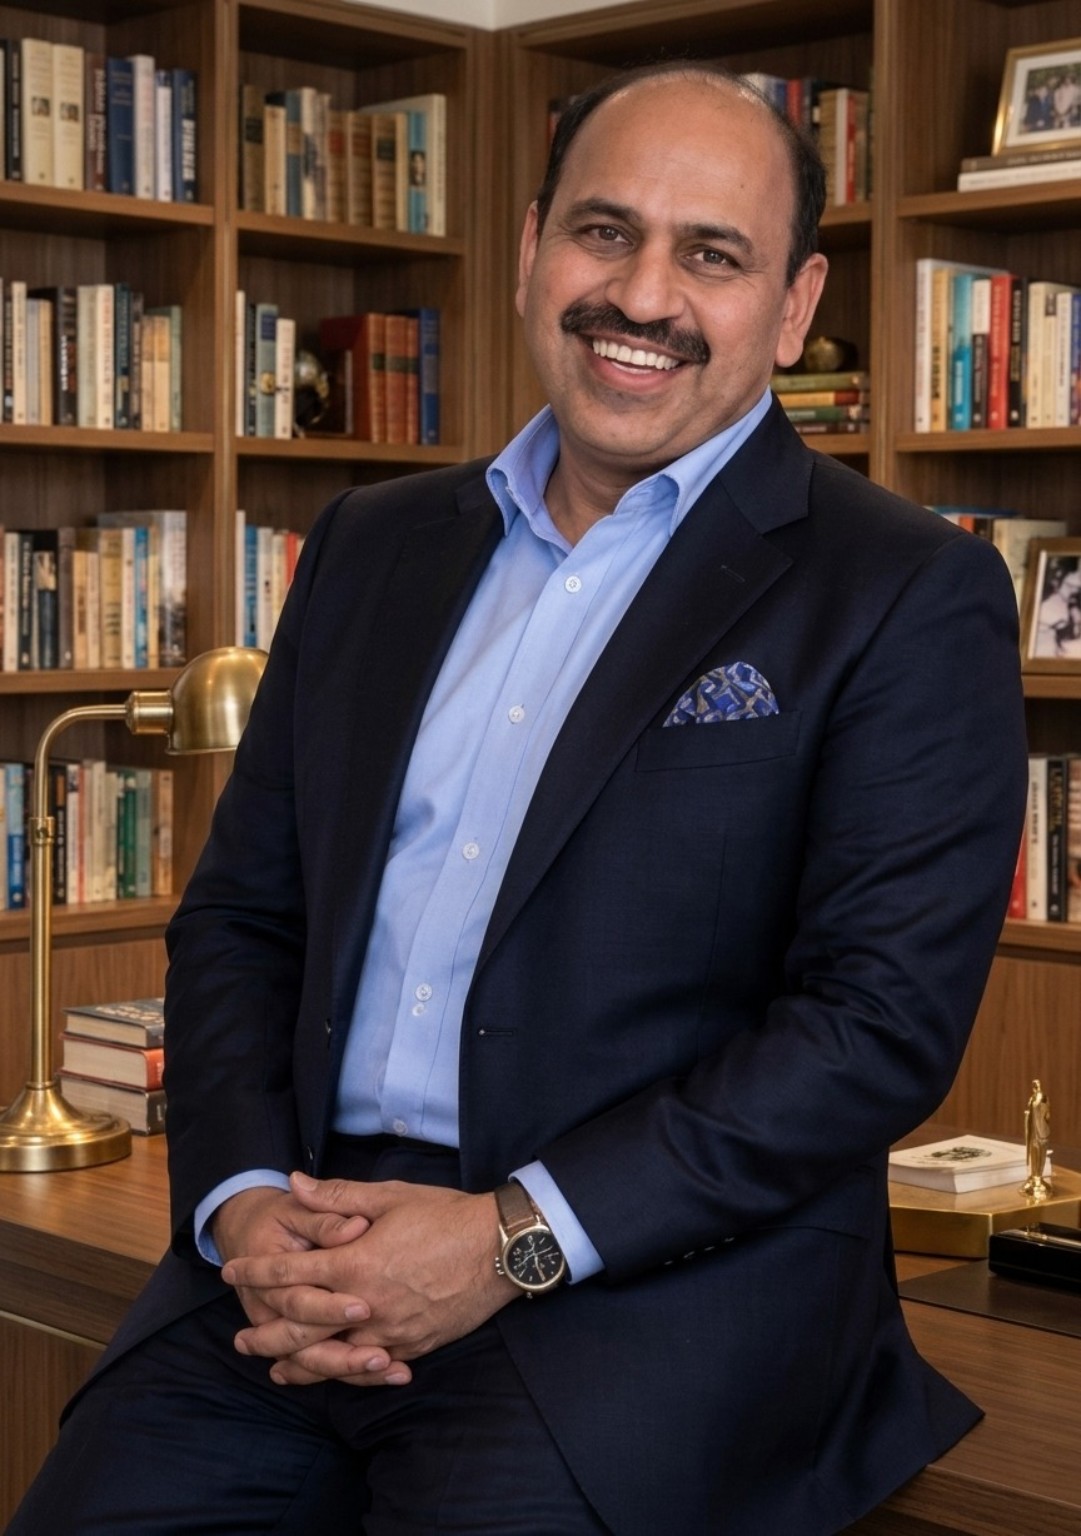
Qamar Zia Ahmad
Cluster Manager – Corporate Liabilities Central & North
Bank Alfalah has transitioned from a traditional commercial bank into a digital frontrunner in Pakistan. What forms the architectural backbone of this digital transformation?
Answer: Our digital transformation is anchored on a shift from a monolithic legacy infrastructure to a highly agile, microservices-based architecture. By decoupling our core banking systems from the customer-facing layers through robust API orchestration, we can develop, test, and deploy features independently. This architectural flexibility powers the Alfa Mobile App, allowing us to roll out real-time updates, handle massive transactional concurrency, and maintain a 99.9% uptime baseline without disrupting backend ledgers.
The retail banking landscape is heavily driven by consumer convenience. How has Bank Alfalah optimized the digital onboarding experience for retail customers?
Answer: We built a frictionless onboarding journey leveraging the State Bank of Pakistan’s (SBP) Asaan Digital Account framework. By integrating our frontend directly with NADRA for real-time biometric verification and using Optical Character Recognition (OCR) for document scanning, a customer can open a fully functional bank account within minutes via the Alfa App. We have effectively removed the physical branch constraint, converting customer smartphone cameras into instant KYC (Know Your Customer) portals.
Interoperability is a major challenge in Pakistan’s financial ecosystem. How is Bank Alfalah leveraging the ‘Raast’ instant payment system?
Answer: Raast has been a paradigm shift for instant payments in Pakistan, and Bank Alfalah was among the earliest adopters to deeply embed it into our transaction matrix. We have mapped Raast aliases (like mobile numbers) directly to our Core Banking System (CBS) routing tables. This allows our customers to execute Peer-to-Peer (P2P) transfers, Person-to-Merchant (P2M) payments, and bulk dividend payouts instantly with zero transaction friction, drastically reducing reliance on traditional, slower clearing mechanisms.
Security is the primary concern for users adopting digital banking. What advanced security protocols protect Bank Alfalah’s digital channels from cyber threats?
Answer: We employ a multi-layered security paradigm. At the device level, we enforce strict hardware cryptographic binding and biometric authentication (FaceID/Fingerprint). For transactional security, our systems utilize EMV 3-D Secure (3DS) protocols coupled with real-time, AI-driven fraud detection systems that analyze transaction velocity, location anomalies, and behavioral patterns. Furthermore, all data in transit and at rest is secured via advanced AES-256 encryption, ensuring that customer payloads remain completely compromised-proof.
Bank Alfalah’s ‘AlfaMall’ is a unique integration of e-commerce within a banking application. What was the strategic and technical objective behind this ecosystem?
Answer: The objective behind AlfaMall was to evolve Bank Alfalah from a mere transactional utility into an embedded finance ecosystem. Technically, AlfaMall integrates third-party merchants directly into our banking rails via secure APIs. This enables unique financial products at checkout, such as buying products on 0% Buy Now, Pay Later (BNPL) installment plans utilizing the customer’s pre-approved credit limits, or redeeming Alfa Orbits directly as cash equivalents. It closes the loop between lifestyle, ecommerce, and digital liquidity.
Could you explain the technical mechanics of the ‘Alfa Orbits’ loyalty program and how it drives digital customer retention?
Answer: Alfa Orbits are engineered as a digital ledger asset within our loyalty management subsystem. Every time a customer performs a digital action—be it a bill payment, a QR scan, or a debit card swipe—our rewards engine automatically calculates and credits Orbits based on algorithmic rules. The system supports Split Payment architecture, meaning a user can dynamically pay a LESCO bill or purchase a mobile top-up by funding 50% via cash balances and 50% via Orbits. This instant, tangible valuation of points directly improves customer lifetime value (LTV) and digital retention.
Small and Medium Enterprises (SMEs) often struggle with traditional payment acceptance. How has Bank Alfalah digitalized merchant acquiring?
Answer: We have heavily democratized merchant acquiring through our Alfa QR and Alfa Pro digital solutions. By deploying low-cost, dynamic and static QR codes built on interoperable SBP standards, micro-merchants can accept digital payments without expensive POS hardware. For larger enterprises, our payment gateway features plug-and-play SDKs and APIs that seamlessly integrate into websites and apps, providing merchants with a consolidated, real-time dashboard to monitor settlement pipelines and merchant cash flows.
Corporate and institutional clients have radically different needs compared to retail consumers. How does your digital strategy cater to the corporate sector?
Answer: For corporate entities, we deploy Alfa Biz and specialized Corporate Internet Banking portals. These platforms support complex corporate governance workflows, such as multi-level approval matrices, bulk payroll processing, and automated vendor payments. We also offer Host-to-Host (H2H) integration, directly linking a corporate client’s ERP software (like SAP or Oracle) with Bank Alfalah’s transaction processing engine to automate thousands of daily treasury actions securely.
Data is often cited as the new currency. How is Bank Alfalah utilizing Data Analytics and AI to enhance its customer offerings?
Answer: We have deployed an enterprise-grade Data Warehouse and Business Intelligence (BI) framework that analyzes unstructured transactional data into actionable insights. By applying Machine Learning algorithms to spending patterns, transaction histories, and risk profiles, we can execute predictive cross-selling. For example, if the algorithm detects consistent travel bookings, the system preapproves a higher-tier credit card or a tailored travel insurance product, presenting it via in-app banners tailored specifically to that unique user segment.
Looking toward the future, what is Bank Alfalah’s vision regarding Open Banking and the advent of Digital Banks in Pakistan?
Answer: We view Open Banking not as a threat, but as an expansive growth vector. Bank Alfalah is actively developing a robust Open API Sandbox. This allows authorized FinTechs, third-party developers, and digital platforms to securely build financial products on top of our regulated banking infrastructure. As the regulatory landscape introduces fully digital banks to Pakistan, Bank Alfalah is positioned to act as a primary clearing, settlement, and lifestyle infrastructure partner, driving a truly cashless national economy.
